

A home can look affordable on a listing page and still fall outside a lender’s approval range. That gap is why understanding what affects mortgage loan approval matters before you make an offer, set a budget, or plan a move. Mortgage approval is not based on one score or one paycheck. Lenders look at the full financial picture, the property, and whether the loan fits program guidelines.
The good news is that most approval factors are visible well before closing. With the right preparation, buyers can identify issues early, choose a realistic price range, and avoid having financing become a last-minute obstacle.
What affects mortgage loan approval?
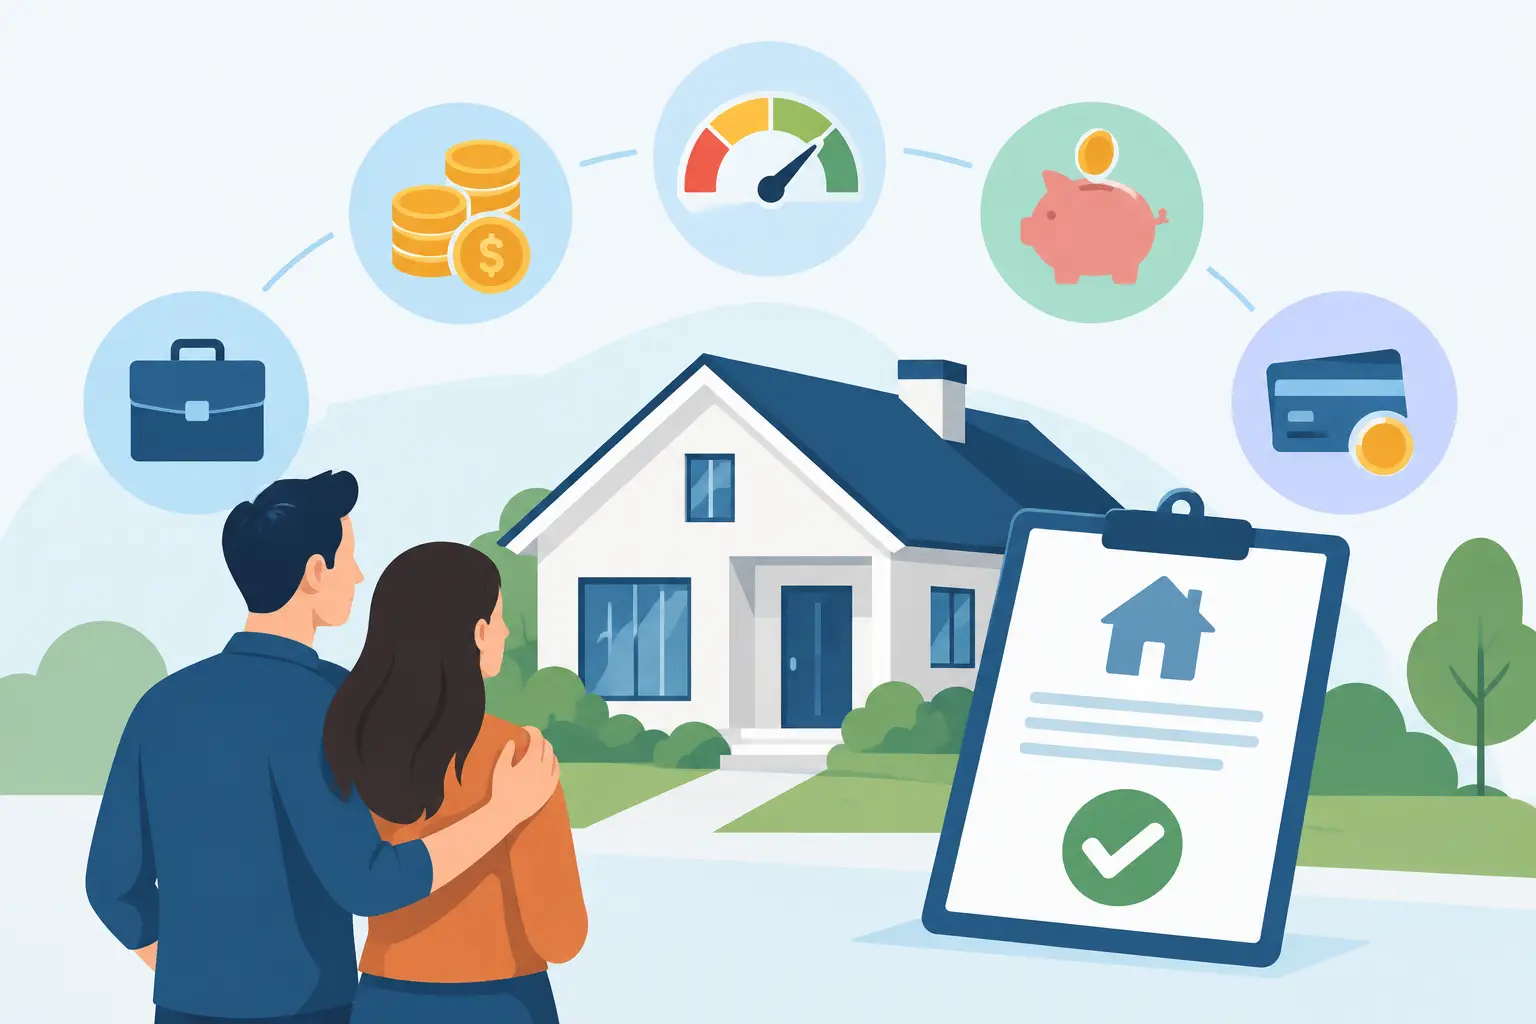
At its core, a lender is evaluating two questions: Can you reasonably repay this loan, and does the home provide acceptable collateral for the amount being borrowed? Your credit, income, debts, available funds, loan type, and property details all help answer those questions.
Approval standards vary by lender and loan program. A borrower who does not qualify for one conventional loan may be eligible for an FHA, VA, USDA, or portfolio option, depending on the situation. The goal is not simply to find a loan with the lowest advertised rate. It is to match the financing structure to your finances, timeline, and home purchase plans.
Credit history and credit score
Credit scores give lenders a quick view of how you have handled borrowed money. Higher scores can improve your access to loan programs, interest rates, and lower down payment options. But the score is only part of the review.
Lenders also examine the report behind it. They may consider late payments, collection accounts, charge-offs, bankruptcies, foreclosures, and how recently any of those events occurred. A single old late payment generally has a different effect than repeated recent delinquencies.
Credit utilization can matter, too. If revolving balances are close to the limits on your credit cards, your score may be lower and your monthly debt obligations may appear less manageable. Paying down balances before applying can help, but do not close long-standing accounts without asking a mortgage professional first. Closing an account can reduce available credit and sometimes change your score in an unexpected direction.
Avoid opening new credit accounts while preparing to buy. A new car loan, furniture financing, or several credit inquiries can affect your credit profile and debt-to-income ratio. Even after preapproval, lenders may recheck credit before closing.
Income, employment, and consistency
Income is not just about the number shown on your salary offer or recent pay stub. Lenders need to verify that your income is stable, documented, and likely to continue. For many salaried employees, this includes pay stubs, W-2 forms, and employment verification.
For self-employed buyers, independent contractors, commission-based employees, and investors, the process can be more detailed. Tax returns, business records, and year-to-date profit-and-loss statements may be used to establish qualifying income. A strong revenue month does not always translate into qualifying income if business expenses reduce the taxable amount.
Employment changes are not automatically a problem. Moving from one employer to another in the same field, receiving a promotion, or starting a position with a higher stable salary may be workable. However, a gap in employment, a shift from salary to variable commission, or a move into self-employment shortly before closing can require additional review. Discuss a planned career change before assuming it will not affect your loan.
Debt-to-income ratio and monthly obligations
Your debt-to-income ratio, often called DTI, compares your monthly debt payments with your gross monthly income. The exact calculation and acceptable limit depend on the loan program, credit profile, down payment, and lender guidelines.
Monthly obligations commonly include the proposed housing payment, auto loans, student loans, personal loans, credit card minimum payments, and court-ordered payments. The proposed housing payment is broader than principal and interest. It may also include property taxes, homeowners insurance, mortgage insurance, and applicable homeowners association dues.
This is why a borrower can earn a solid income and still qualify for less than expected. High recurring debt can reduce buying power. In some cases, paying off a small monthly obligation improves qualification more than adding the same amount to a down payment. The best choice depends on the full application, available reserves, and the loan program.
Down payment, closing costs, and cash reserves
A lender wants to confirm where your funds are coming from and that they are available for closing. Your down payment is one piece of the picture. You also need to account for closing costs, prepaid taxes and insurance, earnest money, moving expenses, and repairs or improvements after purchase.
Bank statements are reviewed carefully. Large deposits may need an explanation and documentation showing the source of the money. This is not meant to create unnecessary friction. Mortgage rules require lenders to verify that funds are legitimate and not undisclosed borrowed money.
Gift funds may be allowed under many loan programs, particularly for primary residences, but they must be documented correctly. Some loans also require cash reserves after closing, especially for investment properties, second homes, or borrowers with multiple financed properties. Reserves show that you may be able to continue making payments if an unexpected expense or temporary income disruption occurs.
The home itself affects approval
Mortgage approval is tied to both the borrower and the property. A lender typically orders an appraisal to assess the home’s market value and confirm that it supports the purchase price and loan amount. If the appraisal comes in below the agreed price, the buyer and seller may need to renegotiate, the buyer may bring in more cash, or the transaction may not proceed under the original terms.
Property condition can also matter. Certain loan programs have minimum property standards related to safety, soundness, and livability. Peeling paint, roof concerns, electrical issues, damaged steps, or missing appliances can create appraisal conditions, particularly with government-backed financing.
Condominiums and homeowners associations add another layer. The lender may review the project’s insurance, budget, owner-occupancy levels, pending litigation, and assessment history. A buyer can be financially well qualified while the condo project itself does not meet the lender’s requirements.
Loan program and occupancy matter
How you intend to use the property changes the financing review. A primary residence often receives more favorable terms than a second home or investment property because borrowers are generally expected to prioritize payments on the home where they live.
Loan type matters as well. Conventional, FHA, VA, and other programs have different rules for credit, down payment, mortgage insurance, property condition, and eligible borrowers. A larger down payment can strengthen an application, but it is not always the right move if it leaves the buyer with little cash after closing.
This is where coordinated planning helps. The home search, offer strategy, estimated payment, and loan structure should be aligned before a buyer is emotionally committed to a property.
Documentation and timing can change the outcome
Mortgage lending runs on documentation. Missing pages, outdated bank statements, unexplained deposits, or conflicting information can delay underwriting even when the borrower is otherwise qualified. Responding quickly and accurately to document requests helps keep the process moving.
Timing matters because financial circumstances can change between preapproval and closing. Try to avoid major purchases, new debt, job changes, unusual transfers of money, or missed payments during that period. If something does change, share it early. A surprise discovered near closing is harder to solve than an issue addressed at the start.
Preapproval is a valuable planning tool, but it is not a final loan commitment. Final approval depends on a complete review of income, assets, credit, title, appraisal, and the property itself.
How to prepare before applying
Start by reviewing your credit report and monthly obligations several months before you plan to buy. Gather recent income and asset documents, keep account activity easy to explain, and build a budget around the full monthly payment rather than just the loan principal and interest.
It also helps to have real estate and mortgage conversations connected from the beginning. OPEAM Group brings property representation and mortgage guidance under one roof, helping buyers evaluate homes with a clearer view of financing, payment ranges, and closing requirements.
The most useful next step is a realistic preapproval conversation before you begin touring homes. It gives you room to make decisions with facts in hand, protect your timeline, and focus your search on a home that fits both your life and your financing.